How We Got Here
How Railways and Telegraphs Built a First Global Market
Cheap inland transport and near-instant price information turned separated regional markets into connected ones during the nineteenth century, and the mechanism explains modern price convergence too.
Two nineteenth-century technologies did more to integrate world markets than any trade agreement of the period. Railways moved goods inland cheaply, and telegraphs moved prices instantly.
Inland transport was the binding constraint
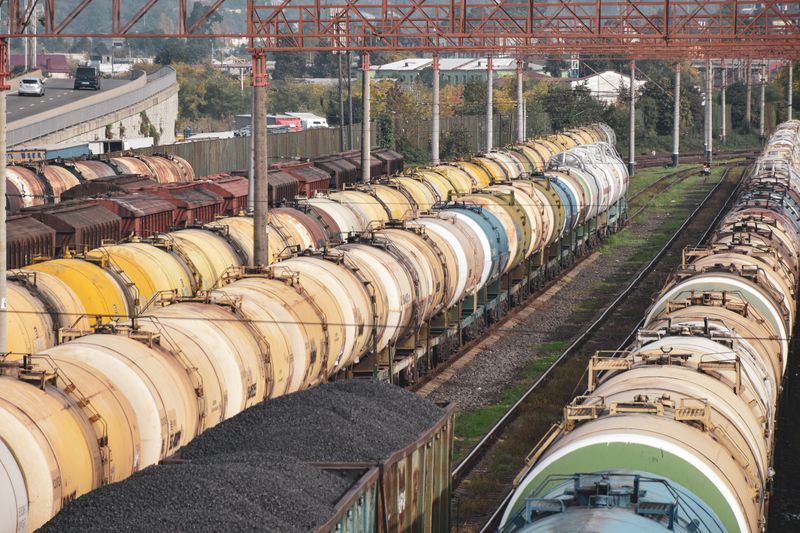
Sea freight had been comparatively cheap for centuries, but moving goods from a port to an interior region was slow and expensive enough to isolate inland markets.
Railways reduced that cost by a large factor and made it predictable, which brought interior producing regions into contact with distant consuming ones for the first time.
Grain grown far from any coast could now reach export markets, and the effect on prices in both the producing and the importing regions was substantial.
Information moved before the goods
Before the telegraph, a merchant learned a distant price weeks after it was set, so trading decisions were made on stale information and carried the risk of a market having moved.
Telegraph links reduced that delay to hours, allowing buyers and sellers in different continents to negotiate against the same price at the same time.
That shared information is what allows prices in separated markets to converge, since a gap wider than transport cost becomes visible immediately and invites arbitrage.
Convergence has a measurable signature
When two markets become connected, the price difference between them narrows towards the cost of moving goods between them, and stops narrowing there.
The remaining gap is transport, insurance and the cost of financing goods in transit, which is why price differences persisted even after integration.
This relationship is the same one that governs regional price differences today, with the numbers changed rather than the mechanism.
The adjustment was disruptive
Producers who had been protected by distance found themselves competing with distant suppliers whose costs were lower, and some regional industries contracted sharply.
Agricultural regions in importing countries faced the most direct pressure, and the political response included tariffs introduced specifically to offset the new transport advantage.
The pattern of a technological change producing both aggregate gains and concentrated local losses recurs throughout trade history, and the policy responses tend to resemble each other.
Institutions grew around the connection
Reliable distant trading required standardised grades, so buyers could purchase goods they had not inspected, and organised exchanges developed to define and enforce them.
Futures trading emerged in the same period, giving producers and merchants a way to fix prices against the delay between shipment and sale.
These institutions were responses to the specific problems that fast information and cheap transport created, and they remain the framework commodity trading operates in.
Questions readers ask
Do exchange rates determine trade balances?
They influence relative prices and therefore trade flows, with long lags and considerable variation across sectors. Savings and investment patterns are generally considered the larger determinant of overall balances.
Why does correspondent banking matter for trade?
Because cross-border payments move through chains of banking relationships. If institutions withdraw from a market, settling transactions becomes difficult even where trade is entirely permitted.
Also by Sunil Bharadwaj
- Percentage or Per Kilo: Why the Shape of a Duty MattersTariffs & Policy
- The Barriers That Are Not Tariffs and Often Bite HarderTariffs & Policy
- Tariff-Rate Quotas: Two Prices for the Same ProductTariffs & Policy
- The Bullwhip: How a Small Demand Wobble Becomes a Factory ShutdownSupply Chains